Photo credit Jsme MILA on Pexels
by Carly Barker, CLTC
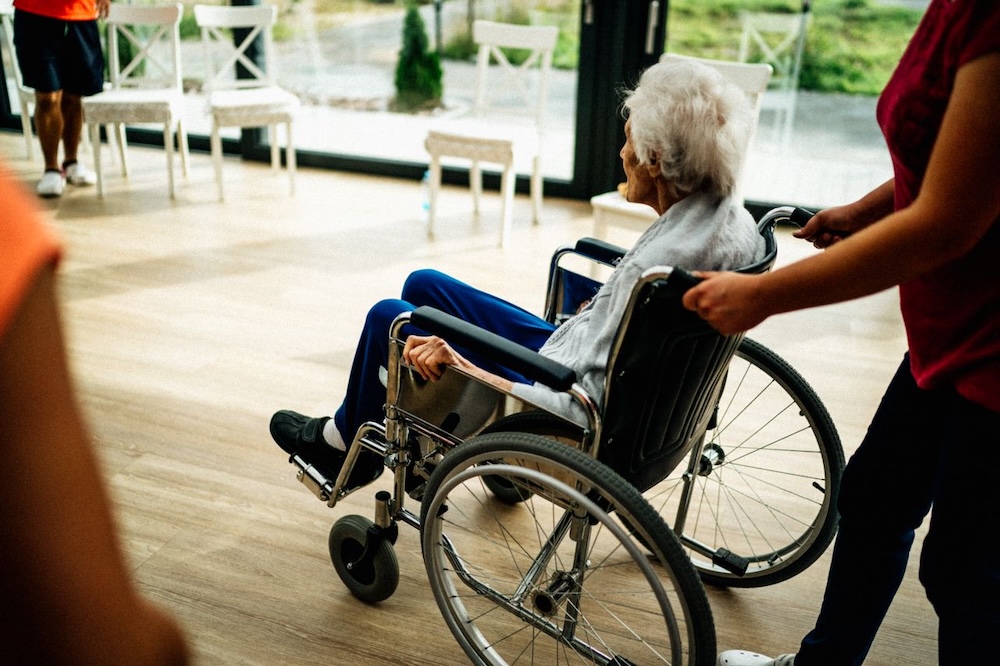
They’re called America’s “invisible workforce” — and you likely know at least one member, or are one yourself. I’m talking about family caregivers. These are people who may have demanding careers, but are forced to cut back or put them on hold to care for ailing or aging parents. The caregiver role may not be a full-time job, and it may be shared with another family member. However, regardless of its structure, it places an enormous burden on families.
For better or worse, the bulk of caregiving for the elderly, ailing, and disabled falls on women. Culturally, women bear the primary responsibility for the home and the kids — all while managing their own careers. And it’s women again who primarily help relatives when they are too old or sick to care for themselves. This is the Sandwich Generation: They’re stuck between caring for their kids and parents.
One of my clients is an attorney who was on the fast track to becoming a partner at a prestigious national firm. She worked hard to get there — she made Phi Beta Kappa at Stanford, graduated from Harvard Law School, and spent years in the trenches working 12- to 14-hour days. An only child from a modest background, her mother died when she was very young. She and her father were very close. He worked two jobs to pay for her prestigious education, and he was extraordinarily proud of his accomplished lawyer daughter.
But then her father was being treated for a very aggressive form of cancer. His income had gone to pay for her education, not disability insurance or long-term care insurance, and he required a lot of care. His medications left him disoriented, so he was no longer able to drive. He needed help with the daily routines of bathing, preparing meals, and taking his medications. His daughter knew that it was her turn to take care of the father who had always been there for her. She took a leave of absence from her law firm. While she knew she’d be able to return to her job, she also knew she was taking a chance with her career.
Thanks to advances in modern medicine and technology, our life expectancy has increased significantly. This is great if we’re fortunate enough to stay in good health and if we have the financial security to enjoy the extra years. We all want to grow old gracefully and die peacefully in our sleep. Sadly, for most of us, that is unlikely. The reality is that most of us will require assistance in our later years to carry out the basic tasks of living.
Unfortunately, on a fairly regular basis, I receive inquiries about long-term care insurance from people who are already in the midst of treatment and not eligible for coverage. If only they had contacted me sooner… Now they’ll need to rely on family, friends, and the nest egg they had hoped would provide a nice cushion for enjoyment – not for personal care.
Those family members needing help might have been able to stay on their own longer had some planning been done and long-term care insurance been purchased earlier on, when they could have qualified. Fortunately, now there are many interesting options in the long-term care insurance market. By doing a little homework, in essence, a person can craft a plan to fit a budget. Some plans have life insurance attached, where benefits are paid if a person dies before needing care.
For those who are already immersed in the caregiving role, don’t be shy about asking for help. As they remind us on airplanes, you need to take care of yourself before you can take care of others. If you know a caregiver, reach out to see if there’s anything you can do to help. It might be something as simple as reading to the parent or family member a few times a week to give the caregiver a much-needed break. Sometimes, simply reaching out to check in can make all the difference in a person’s day.
For more information, contact Carla-Jean Barker at http://www.cjbins.com